Your Costco 401(k) at Retirement: Keep It, Roll It Over, or Look at NUA First
Learn when to keep your Costco T. Rowe Price 401(k) at retirement, when an IRA rollover makes sense, and why NUA should come first if you own Costco stock.
If you've spent 20 or 30 years at Costco, there’s a good chance your T. Rowe Price 401(k) is one of the biggest things you own and it's also probably the nest egg you plan to live on. So the choices you make with it as you get close to retirement carry a lot of weight, and at least one of them is a one-way door.
Your options for a Costco 401(k)
On paper you have three choices. You can:
- Leave the money in the Costco plan with T. Rowe Price,
- Roll it into an IRA
- Withdraw the whole balance
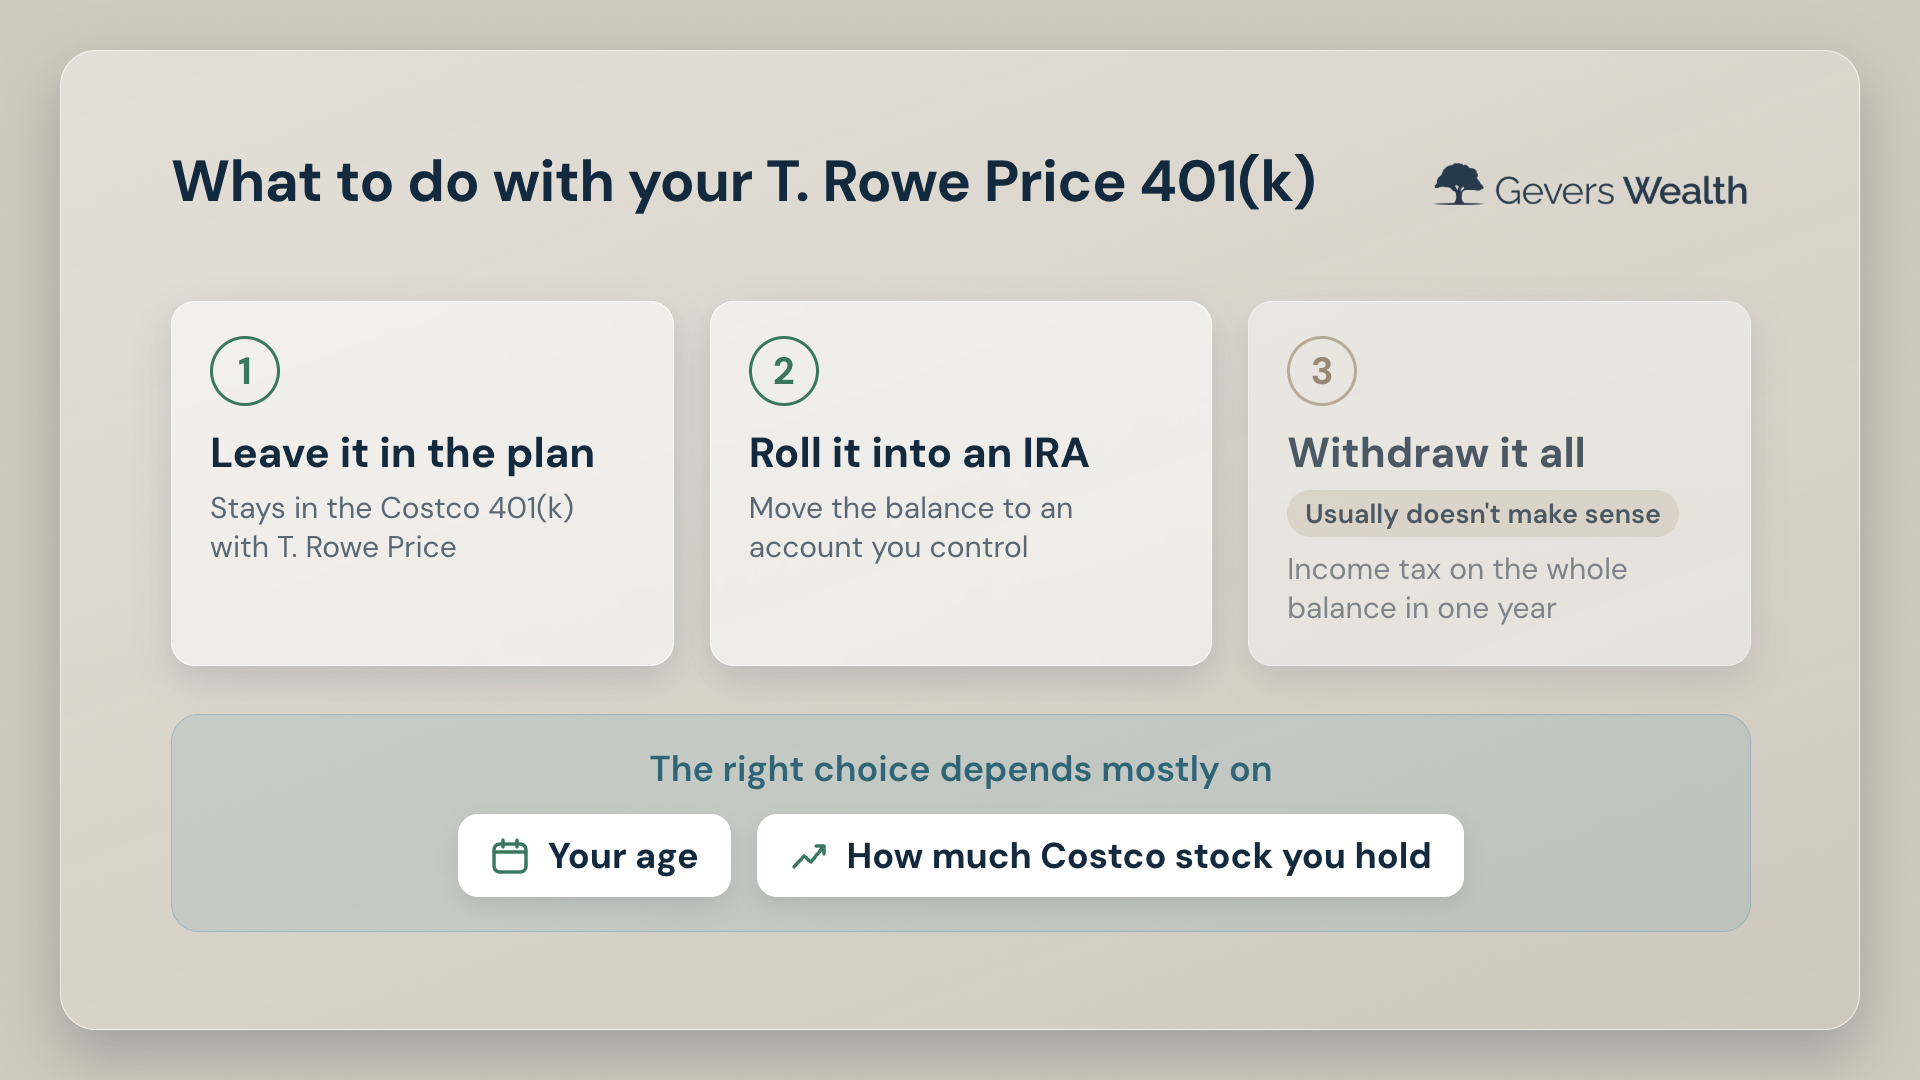
Taking it all out at once usually means paying income tax on the entire amount in a single year, so for most people that isn't a real option. That leaves two, and the right one depends mostly on your age and on how much Costco stock you hold.
When keeping it in the plan makes sense
A lot of tenured Costco employees reach a point where they could retire a little early, around 55. We recently worked with a 55-year-old who'd been at Costco for 33 years and realized his savings were big enough to make the jump.
Age matters primarily because of one tax rule. If you leave your employer in or after the year you turn 55, withdrawals from that employer's 401(k) generally avoid the 10% early withdrawal penalty.¹ An IRA doesn't have that exception, so once the money is rolled over, most withdrawals before 59½ come with the penalty.² There are workarounds, but they're complicated and unforgiving if you get them wrong.
For him, the answer was to keep the whole balance with T. Rowe Price until 59½ so he could take income freely in the meantime. If you're retiring before 59½, that's worth serious thought before you move anything.
Some people also simply like the investments in the plan, often a T. Rowe Price target date fund. That can be fine. Look at what those funds cost, though, because target date funds can carry fairly high internal expenses, and compare that with what you'd pay in an IRA.
The tax strategy to look at first: NUA
If you hold a lot of Costco stock in your 401(k), look at taxes before you decide anything else. A strategy called net unrealized appreciation, or NUA, can apply to Costco employees more than most, for two reasons. Costco lets you buy company stock inside the 401(k), and for years they let people put their entire 401(k) into it. And many employees have held those shares for decades.
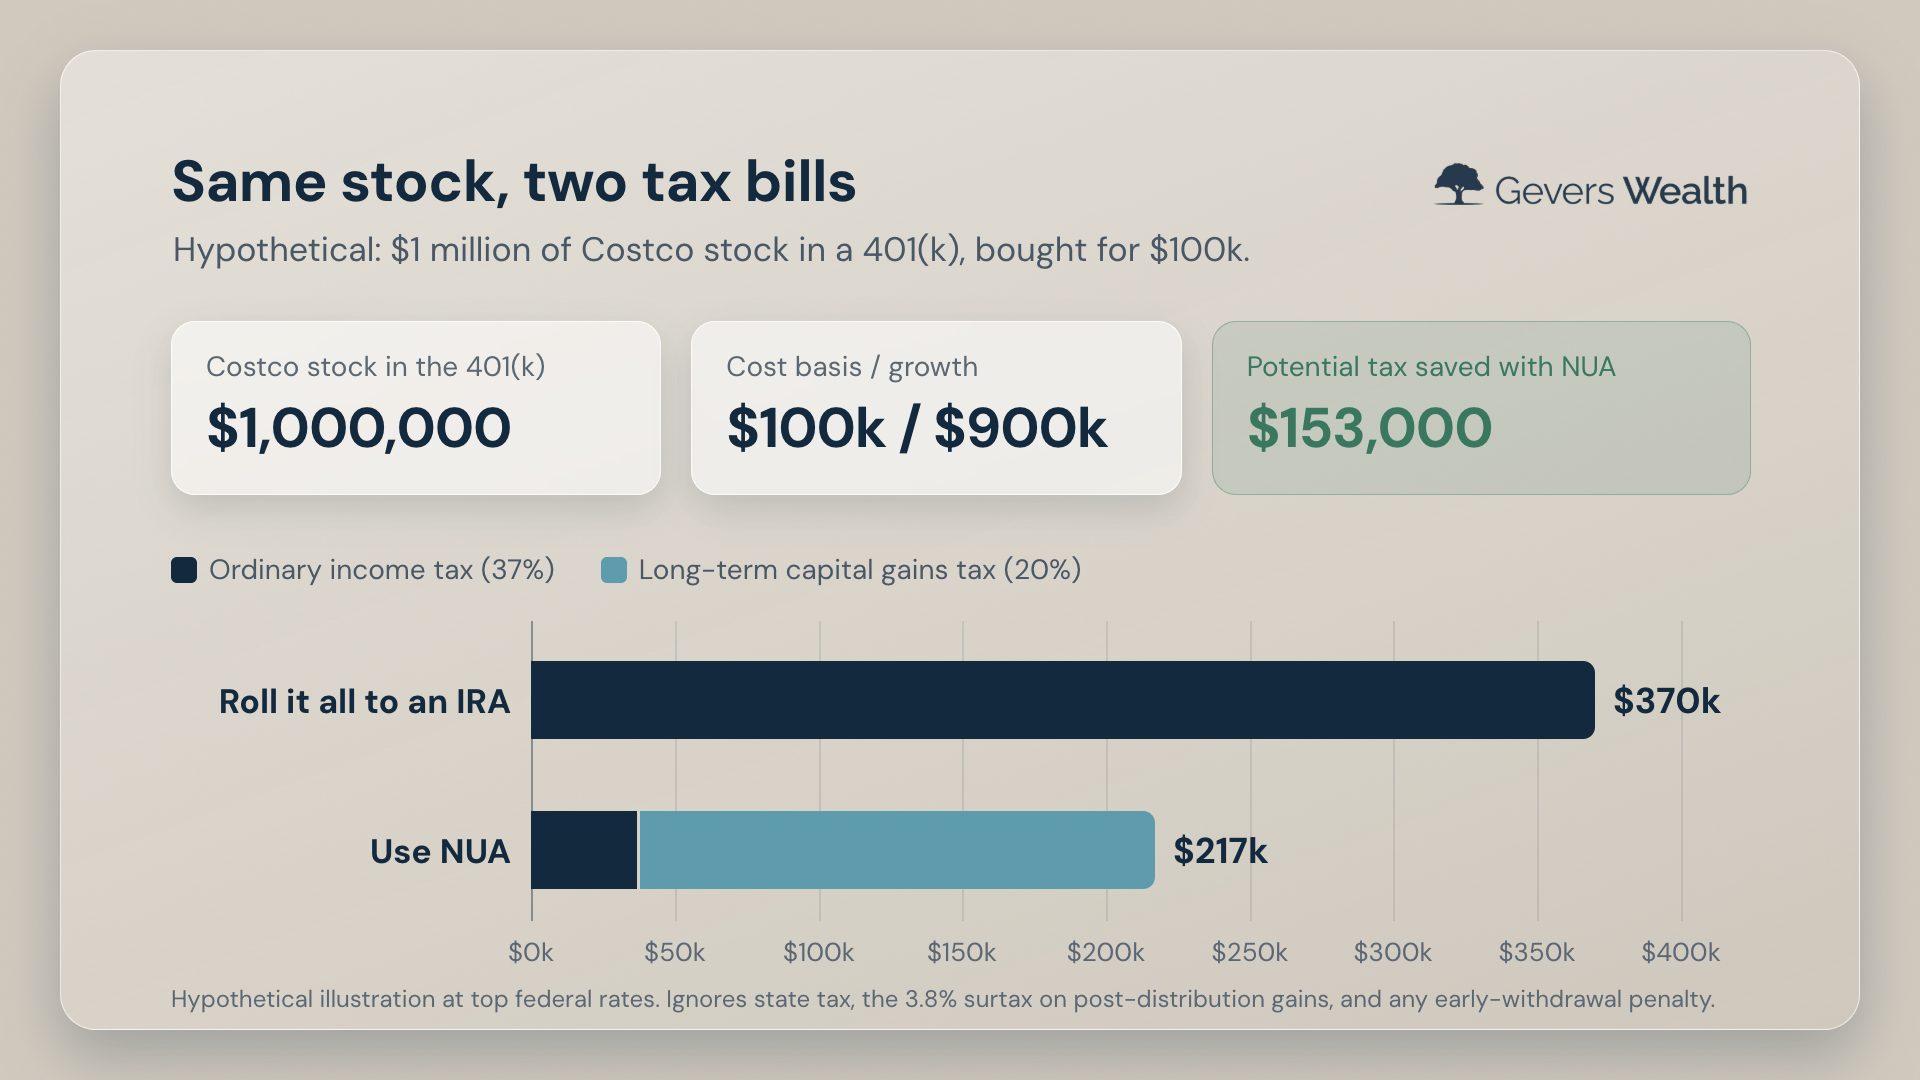
Normally every dollar you withdraw from a 401(k) or an IRA is taxed at ordinary income rates.
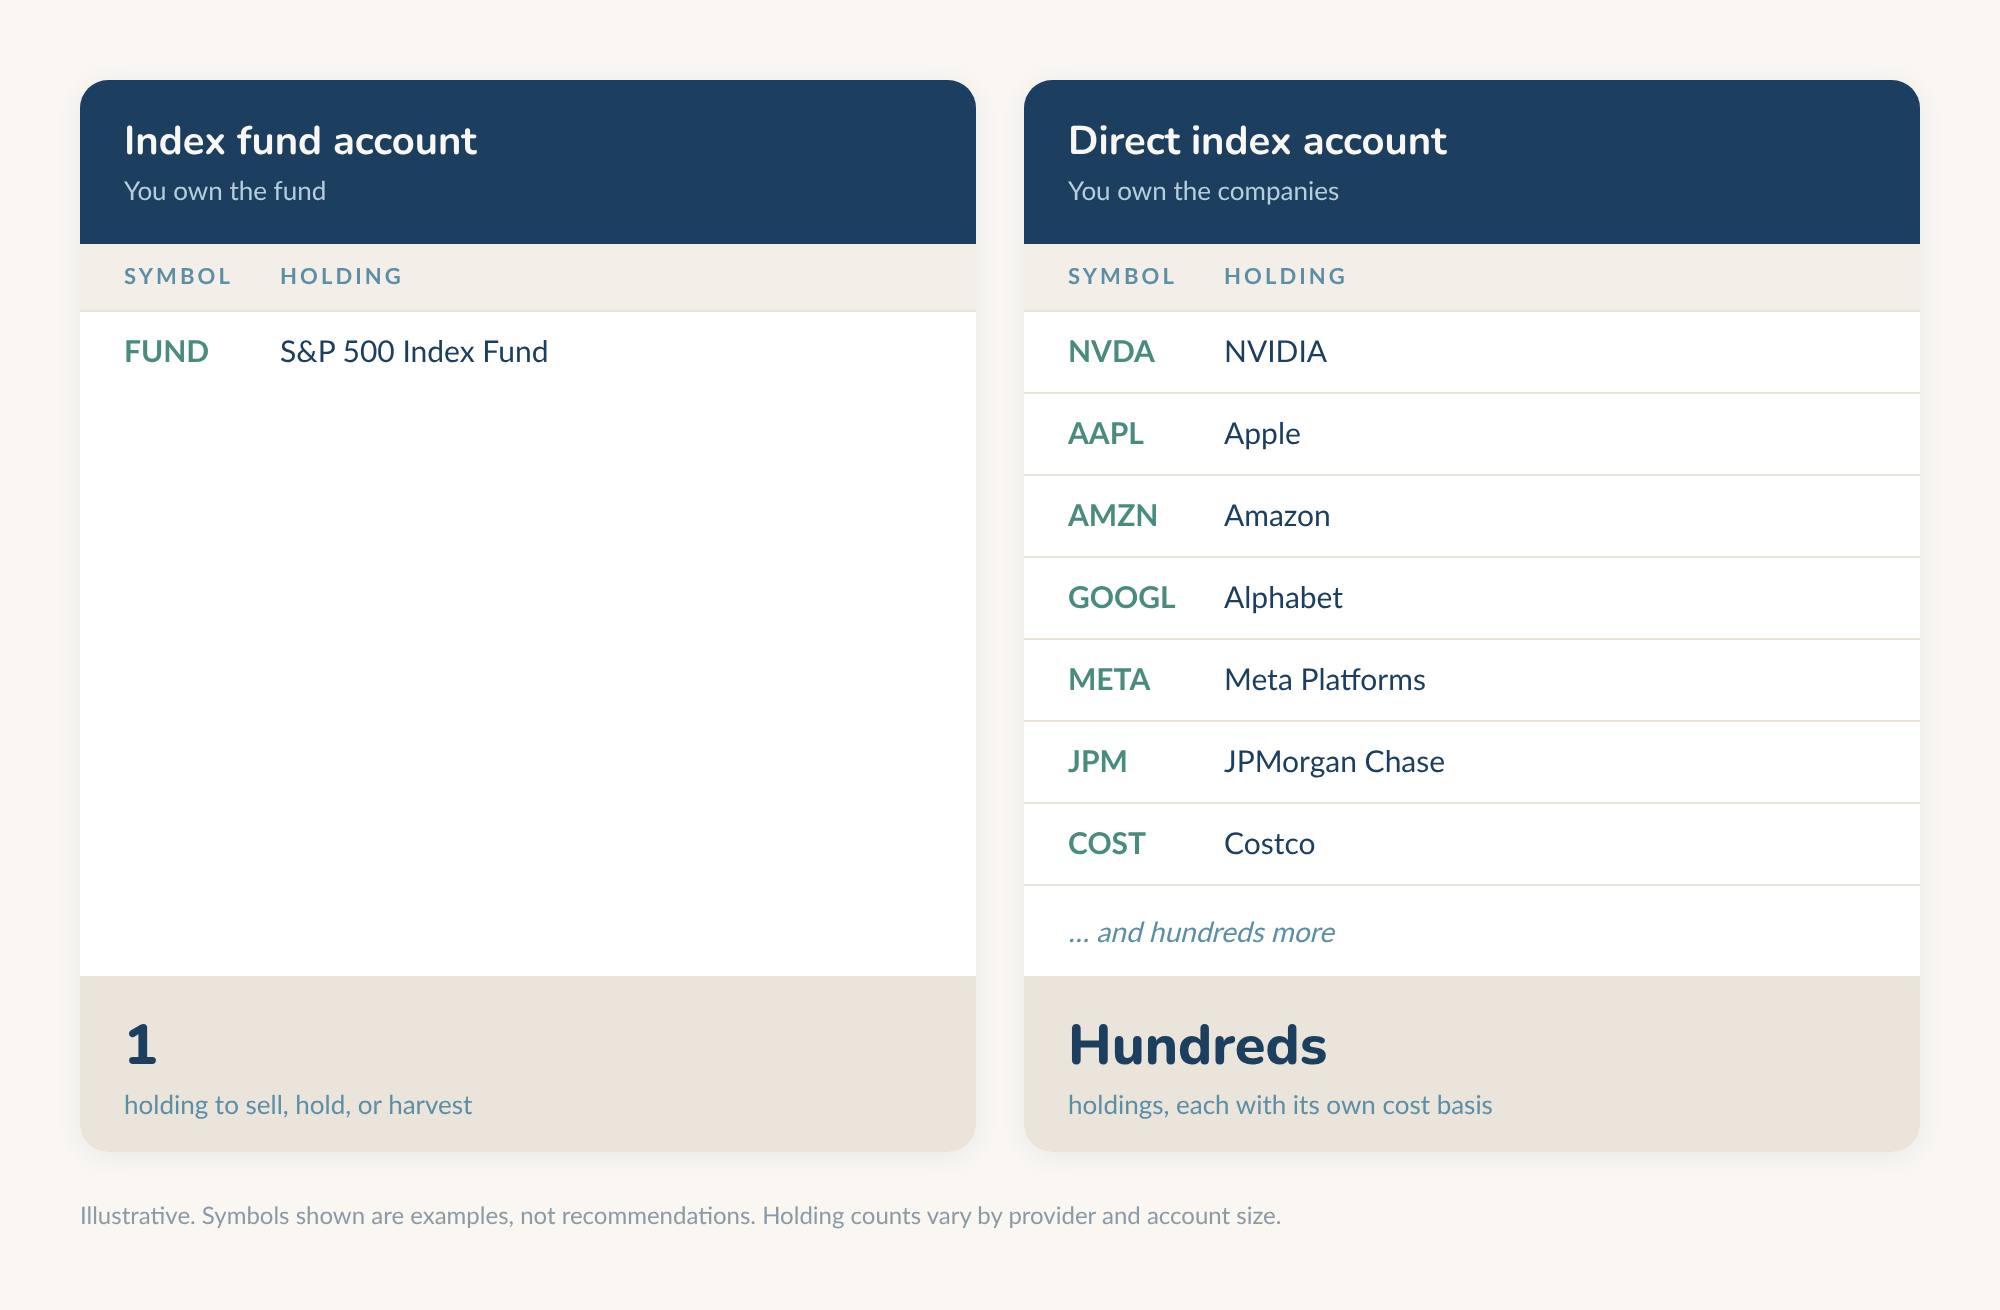
NUA lets you move the Costco stock out separately, into a regular taxable brokerage account, while the rest of the plan goes to an IRA. You pay ordinary income tax on what you originally paid for the shares, your cost basis. The growth above that can be taxed at long-term capital gains rates when you sell.³ The top capital gains rate is well below the top ordinary income rate, so for a long-held position the difference can be large.
The order of operations matters. NUA generally requires distributing the plan in a single tax year after a triggering event such as leaving Costco or reaching 59½, with the stock moved in kind rather than sold first.³ If you roll your 401(k) into an IRA first, the NUA option on those shares is gone for good.
Rolling your Costco 401(k) into an IRA
The second path is a rollover. You can open an IRA with the custodian of your choice or work with an advisor. A rollover isn't taxed as long as the money lands in the IRA within 60 days.⁴ The simplest way is a direct rollover from the plan to the IRA, because an indirect rollover paid to you has 20% withheld for taxes.⁵
We recently helped a Costco employee with about 30 years at the company, who had been in the T. Rowe Price plan his whole career. He and his wife were nervous about making any change. We built a full plan with them, showed them where their income would come from and what investment mix fit their retirement, and then moved his 401(k) into an IRA we manage for them.
The case for an IRA comes down to choice and convenience. Your investment menu goes from a short list of funds to almost anything publicly traded. Day-to-day logistics, like setting up monthly withdrawals, doing Roth conversions or changing your mix, tend to be easier with a large IRA custodian.
The trade-offs are the ones above. Before 59½, IRA withdrawals usually carry the 10% penalty, and a rollover ends any chance to use NUA on your Costco stock.
Two things to check before you decide
Start with your age. If you're leaving Costco before 59½, keeping the 401(k) where it is may be the better move for now. Then look at your Costco stock. If you have a large position that has grown a lot, look closely at NUA before you roll anything over.
If you'd like help looking at your own Costco 401(k), we're a mile down the road from Costco headquarters in Issaquah. Book a no-pressure intro meeting. If we're not the right fit, we'll tell you.
Frequently asked questions
Can I take money from my Costco 401(k) at 55 without a penalty?
Generally yes, if you leave Costco in or after the year you turn 55. Withdrawals from that 401(k) avoid the 10% early withdrawal penalty, though income tax still applies.¹
What is net unrealized appreciation (NUA)?
A tax treatment for company stock held in a 401(k). You pay ordinary income tax on your cost basis when the shares move to a taxable account, and the growth can be taxed at long-term capital gains rates when you sell.³
Can I still use NUA after rolling my 401(k) into an IRA?
No. Once the Costco stock has been rolled into an IRA, the NUA option on those shares is gone.
Is rolling my 401(k) into an IRA taxable?
Not if the money reaches the IRA within 60 days.⁴ A direct rollover is the simplest route, because an indirect rollover paid to you has 20% withheld.⁵
¹https://www.irs.gov/taxtopics/tc558
³https://www.irs.gov/publications/p575
⁵https://www.irs.gov/taxtopics/tc413
Disclosure:
Gevers Wealth Management, LLC is an investment adviser registered with the Securities and Exchange Commission. This article is educational and is not individualized tax or investment advice. The client stories are simplified, and your situation may differ. Tax rules change; coordinate any decision about your 401(k) with your CPA.Gevers Wealth Management is an independent investment adviser and is not affiliated with, endorsed by, or sponsored by Costco Wholesale Corporation.
Trey Gevers CFP®
Trey Gevers is a CERTIFIED FINANCIAL PLANNER™ and managing partner at Gevers Wealth in Issaquah, WA, specializing in helping people navigate retirement with clarity and confidence. He's known for turning complex financial strategies into plans that are actually easy to understand — because he believes a great plan should build your future and let you enjoy the life you're living right now.
Continue Reading
Discover additional articles to help you stay informed and make thoughtful financial decisions over time.













Book a Free Assessment Today
Set up a relaxed introductory call to see if we are a good fit.